Showing posts with label macro data among 10 things to keep investors busy. Show all posts

Sunday, 11 February 2018

Market Week Ahead: Earnings, macro data among few things to keep investors busy

Experts advise churning portfolio and buying quality stocks in this dip. They expect the stock specific action to continue as we are near fag end of December quarter earnings season.


Bears disrupted the extended reign of bulls on Dalal Street, dragging down benchmark indices over 5.5 percent in two consecutive weeks, and in effect, aligning market valuations with earnings and economic growth.
A sell-off, warranted for a long time, was eventually caused by two events – first, the Budget 2018 where government imposed 10 percent long term capital gains tax on equity and 10 percent dividend distribution tax on equity oriented MF, and raised fiscal deficit target; and second global developments where expectations increased for a faster hike in US interest rates (more than three) hinting early inflationary pressures on tight labour market with higher wages. RBI in its policy also cited inflation concerns while keeping repo rate unchanged.
Losses over the last two weeks wiped out the year-to-date gains in 2018 with investors losing Rs 7.79 lakh crore worth of wealth in just the two weeks. The 50-share NSE Nifty had rallied 29 percent in 2017, taking total gains before correction to over 35 percent (i.e. till January 25, 2018) on hopes of earnings and economic recovery.
There was, however, some sigh of relief only in broader markets in the passing week as mid and smallcaps recovered on bargain hunting, with the Nifty Midcap index rising 0.6 percent and BSE Smallcap gaining 1.8 percent (on earnings recovery in Q3FY18) after losing 8 percent in previous week.
Here are things that will keep investors busy next week:
Earnings
We are at the fag end of the earnings season and majority of largecaps as well as midcaps have already declared earnings. Earnings announced, so far, are stable to better-than-expected.
"The current earnings season is providing strong signs of revival in corporate earnings underlining the long term growth prospects, which is providing relief for investors," Vinod Nair, Head Of Research at Geojit Financial Services said.
More than 2,000 companies will announce December quarter numbers in the coming week, which include some PSU banks, engineering & construction, real estate, sugar firms etc.
Monday (566 companies): GAIL, Bank of India, Britannia Industries, Motherson Sumi, Indian Bank, Power Finance Corporation, NHPC, Sadbhav Engineering, Corporation Bank, Mangalam Cement;
Tuesday (504) : DLF, Shipping Corporation, MMTC, JK Tyre, IL&FS Engineering, Abab Offshore, CG Power, Snowman Logistics, Shalimar Paints, Max India, PTC India Financial, NMDC, NBCC, Punjab & Sind Bank, Indian Overseas Bank, Godfrey Phillips India, GMR Infrastructure, Fortis Healthcare, Chambal Fertilizers, Bajaj Hindusthan, Dilip Buildcon, CRISIL;
Wednesday (1,110): Sun Pharma, Tata Power, Grasim Industries, Jet Airways, Dena Bank, Allahabad Bank, DB Realty, Zicom Security, HDIL, Godrej Industries, Vivimed Labs, Satin Creditcare, Sakthi Sugars, Titagarh Wagons, Steel Strips Wheels, Shriram EPC, Speciality Restaurants, Pratibha Industries, PNC Infratech, NLC India, NCC, Rolta India, Repco Home Finance, Shree Renuka Sugars, Religare Enterprises, MT Educare, Rana Sugars, Punj Lloyd, Prism Cement, Patel Engineering, Infibeam Incorporation, Jindal Stainless, IVRCL, JBM Auto, Globus Spirits, Gitanjali Gems, Gammon Infrastructure, Endurance Technologies, GVK Power, GTPL Hathway, 8K Miles, Ballarpur Industries, Bharat Road Network, Bhushan Steel, Ahluwalia Contracts;
Thursday (7): Vesuvius India;
Friday: Varun Beverages.
Sun Pharma
Sun Pharma, which will announce its October-December quarter earnings on Wednesday, is expected to report weak numbers especially due to continued US pricing pressure but domestic numbers could be good.
"Companies like Sun Pharma, while having strong domestic presences will struggle to show growth in Q3FY18 due to the absence of significant launches in the US market. Current regulatory issues for Sun Pharma (warning letter for Halol plant) have stifled launches in the US market in the recent past and we expect this to reflect in the current quarter’s US numbers," HDFC Securities said.
It expects company's topline is likely to decline around 11 percent YoY, owing to the high base (gGleevec) and increasing pressure on Taro’s business. The launch of gCoreg CR (first generic) will mitigate some of the decline, it feels.
Prabhudas Lilladher expects 16.6 percent fall in topline, 47 percent in operating income and 40 percent in profitability while HDFC sees EBITDA margin to continue to show some sequential improvement on the back of QoQ growth in the US business and resulting operating leverage.
Key things to watch out for would be FY19 generic launch guidance, updates on Halol facility re-inspection and specialty pipeline progress.
Taro Pharma, the subsidiary which announced earnings last week, reported 30 percent decline in topline due to price erosion in the US, 87 percent fall in bottomline on one time charge of USD 38 million due to tax changes in US and 1,880 basis points contraction in operating profit margin.
PSU Banks
Country's largest lender State Bank of India, on Friday, reported quarterly loss (Rs 2,416 crore) for the first time in almost 17 years, with higher slippages and weak asset quality performance. Even loan and deposit growth was muted in Q3FY18.
Bank of Baroda also reported a 56 percent fall YoY in profit on higher provisions and marginally higher asset quality.
Stocks may react to bad numbers on Monday, but analysts feel there could be some improvement from Q4 and FY19 onwards in banks earnings. Infact, FY19 could be far better than FY18, they said.
"Worst is behind us and heading into FY19, lot of resolutions in Q1FY18 would clean up the path for corporate banks to move ahead strongly. Next 3-6 months could be challenging but after that there would be greener pasture," Krishna Kumar of Sundaram MF said.
Bank of India, Indian Bank, Corporation Bank, Indian Overseas Bank, Dena Bank and Allahabad Bank will announce quarterly earnings in the coming week.
Macro Data
Industrial and manufacturing production data for December month, and CPI inflation for January will be released on Monday while WPI inflation for January will be announced on Wednesday.
IIP growth in November jumped to 17-month high of 8.4 percent from 2 percent in October while Consumer Price Index inflation increased to 5.21 percent in December from 4.88 percent in previous month.
Balance of trade data for January will be declared on Thursday. Foreign exchange reserves for the week ended February 9, and deposit & bank loan growth for week ended February 2 will be released on Friday.
India’s forex reserves surged by USD 4.1 billion to a new high of USD 421 billion for week ended February 2.
Technical Outlook
Technical analysts feel the underlying trend of the market is still weak and breaking of 10,000 can be possible in short term.
"The trend of Nifty as per weekly and monthly is down. The present weakness is expected to continue in the coming weeks or months. Although Nifty placed at the immediate support of around 10,400 levels, the support could eventually be broken on the downside. One may expect Nifty to slip below the recent low of 10,276 levels," Nagaraj Shetti, Technical Research Analyst at HDFC Securities said.
Any attempt of upside bounce is going to be a sell on rise opportunity for next week and the downside targets to be watched is around 10,000-mark for the next couple of weeks, he added.
According to Ashwani Gujral, ashwanigujral.com, the market is expected to remain choppy in the coming week and 10,300-10,600 could be trading band for the Nifty.
F&O
F&O data also indicated that there could be further weakness in the market going ahead.
"The Call writers in the Nifty have been rolling their positions lower, which suggests towards increasing pressure on the index as we are approaching settlement. Profit booking is seen in 10900 Call writing positions and now these are getting formed at 10500-10600 Call strikes," ICICIdirect said.
It further said, "The pressure due to long liquidation is quite evident in so far outperforming Nifty heavyweights. This may keep the index under pressure for some time. If the Nifty is unable to hold above 10,600, it can slip towards 10,250 again towards settlement."
On Friday, Call writing was seen at the strike price of 10,400, which saw the addition of 7.99 lakh contracts along with 10,500, which added 5.07 lakh contracts, along with 10,600, which saw the addition of 4.22 lakh contracts.
Maximum Put writing was seen at the strike price of 10,100, which saw the addition of 6.94 lakh contracts, followed by 10,200, which added 5.62 lakh contracts and 10,400, which added 3.63 lakh contracts.
IPO
Healthcare services provider Aster DM Healthcare will open its IPO for subscription on Monday, with a price band of Rs 180-190 per share.
The company aims to raise up to Rs 980 per share at higher end of price band, of which it already garnered Rs 294 crore from anchor investors on February 9.
The issue, which will close on February 15, consists of a fresh issue of up to Rs 725 crore and an offer for sale of up to 1,34,28,251 equity shares by the promoter, Union Investments Private Limited.
The fresh issue proceeds would be utilised for repayment of debt; purchase of medical equipment; and general corporate purposes
Stocks in Focus
On coming Monday, State Bank of India, ONGC, Mahindra & Mahindra, BPCL, Bank of Baroda, Marico, Tata Steel, Sobha, Nalco, Sun TV Network, Capacit’e Infraprojects, PTC India, Va Tech Wabag, Amara Raja Batteries, MOIL, Syndicate Bank, Oil India, Suzlon Energy, Technofab Engineering, and RCF stocks will react to their earnings.
SIS India will react positively as the company bagged contract for security arrangements at Commonwealth Games.
Global Cues
On Monday, Indian market may react to the Friday's bounce back on Wall Street on but the sustainability of recovery could be difficult going ahead. The Dow Jones ended 330 points higher on last day of the week.
Japan's Q4 GDP; Europe's Q4 GDP and industrial production for December month, and United States' January CPI will be released on Wednesday.
On Thursday, Japan's December core machinery orders & industrial production; and US' January industrial & manufacturing production data will be announced.
 MORE WILL UPDATE SOON!!
Sunday, 7 January 2018

Market Week Ahead: Infosys and TCS earnings, macro data among 10 things to keep investors busy

Blue-chip companies like Infosys, TCS and IndusInd Bank will announce its Q3 numbers in the coming week.

It was a good start to the year 2018 as benchmark and midcap indices ended the week at fresh record closing high despite higher crude oil prices, driven by positive global cues and progress on PSU bank recapitalisation. Also, hopes of government meeting its FY18 fiscal deficit target of 3.2 percent of GDP boosted sentiment.
The 50-share NSE Nifty settled the weekly session at 10,558.85, up 0.3 percent and the 30-share BSE Sensex rose 0.3 percent to 34,153.85 while the broader markets outshone frontline indices, with the Nifty Midcap rising 1.7 percent.
The market has been trading at premium valuations due to consistent liquidity support and hopes of earnings recovery going ahead.
The positive momentum amid volatility is expected to continue in the coming week as well, but the move is likely to be largely dependent on corporate earnings season that will be kickstarted by TCS, Infosys and IndusInd Bank.
Expectations from Union Budget 2018, which will be presented in the Parliament on February 1, may also keep market volatile. Hence, both these events may point towards more stock specific action in the coming week, according to experts.
"The Budget will create volatility and lots of noise but fundamental solid policy change matters a lot to the direction of the economy and inflation and is therefore important for the markets," Madhav Dhar, Managing Partner of GTI Capital Group, said in an interview to CNBC-TV18.
Vinod Nair, Head Of Research at Geojit Financial Services, said the market was wary of a populist Budget since this is last one before general elections. In the immediate future, market will look for more Budget related cues and as per progress of Q3 results season, he added.
In recent times, higher oil prices, rising inflation and RBI's hawkish stance have been ominous for the market, Nair said.
Here are 10 key factors that keep investors busy next week:-
Earnings
The December quarter earnings season will see the Q3results of blue-chip companies like Infosys, TCS and IndusInd Bank in the coming week.
Generally, corporate numbers are an important indicator of economic growth. After steady earnings recovery in Q2FY18, most analysts expect the second half of FY18 (Q3 and Q4) to give clear directions for FY19 earnings.
The earnings recovery momentum is likely to accelerate in Q3FY18. We estimate PAT of our 230 coverage companies to grow 14 percent YoY (first half of FY18: 2 percent). Unlike previous quarters, earnings growth is likely to be more broad-based.
Key things to track include: a) hit on banks’ treasury income (owing to higher interest rates); b) impact of higher commodity prices on gross margins of consumer companies; c) GST related issues; and d) FX impact on export-oriented sectors such as, IT and pharma, it added.
Infosys
The country's second largest software services provider will announce its first quarterly earnings under newly appointed CEO & MD Salil Parekh on January 12.
Ovearll IT earnings for Q3FY18 are expected to be impacted by furloughs and holiday season but as major global currencies were fairly stable during Q3FY18, currencies are not expected to materially affect revenue growth or margins, Edelweiss said.
Brokerage houses expect Infosys to report revenue growth at around 1-1.5 percent. Impact of weakness in revenue growth for the company would be offset by operational efficiencies.
Kotak expects Infosys to maintain guidance of 5.5-6.5 percent constant currency revenue growth and 23-25 percent EBIT margin.
For all IT companies’ earnings, Edelweiss said it would keenly monitor: 1) Infosys’ strategic roadmap post appointment of new CEO, Salil Parekh; 2) demand commentary in BFSI & retail 3) clients’ budget & pricing in legacy business; 4) traction in digital services; and 5) pace of local hiring in US.
TCS
Tata Consultancy Services, the country's largest IT services provider, will declare its earnings on January 11. Analysts largely expect company's revenue growth at around 1 percent for the quarter.
Revenue growth to be impacted due to sustained softness in BFSI and Retail, while rest business will continue good momentum. EBITDA margins expected to contract by 30bps QoQ on account of seasonal furloughs.
Commentary on client budgets, spends by BFSI and retail clients are key monitorables, it added.
IndusInd Bank
IndusInd will be the first to announce third quarter earnings among largecap banks on January 11. It is likely to give some directions to earnings of other banks.
Largely it is expected to be soft quarter for banks due to softer revenue momentum and elevated credit costs, Edelweiss said, adding earnings of retail-heavy private banks are expected to be stable while corporate-heavy banks are likely to incur elevated credit costs (ageing provisions, provisions on accounts referred to NCLT by RBI).
In case of IndusInd, Kotak expects limited asset-quality stress but divergence, if any, could be reported this quarter. Progress on Bharat Financial acquisition is likely to be discussed, it feels.
The research house expects loan growth at 24 percent YoY, led by steady growth in retail business. NIM will remain stable QoQ supported by higher share of retail loans, it feels.
Macro Data
The data for November industrial production and December CPI inflation will be released after market hours on Friday.
The retail inflation measured by the Consumer Price Index for November had increased to a 13-month high of 4.88 percent, from 3.58 percent in October, mainly due to increase in food and oil prices, while India’s industrial output slowed to 2.2 percent in October as compared with 3.8 percent a month ago.
Foreign exchange reserves data for the week ended January 5 will also be announced on Friday while balance of trade data will be declare on Wednesday.
Crude
Brent crude futures, the benchmark for international oil prices, crossed USD 68 a barrel level for the first time since May 2015 is the key risk for country like India which imports more than 80 percent of oil requirement.
Brent crude futures settled the week below that level, at USD 67.62 a barrel. Experts expect the crude can hit USD 70 a barrel, which is still manageable for India but beyond that the risk will increase in terms of widening fiscal deficit. Not only economy but also companies that are depend upon on crude.
"Presently, Indian economy is under stable state and can manage till crude prices are below USD 70-72, will alarm concern if it sustains above USD 75 for longer time," Yogesh Mehta, VP- Retail Research, MOSL said in an interview to Moneycontrol.
Technical Outlook
After decisive close above 10,550 for the first time may drive the Nifty above 10,600 level but beyond that it needs strong cues (could be in earnings or Budget). After record high levels, some consolidation can't be ruled out, experts suggest. According to them, 10,400 will remain immediate support for the Nifty.
The short term trend of Nifty is positive amidst range bound action. The upper range 10,550-60 levels is placed at the verge of upside breakout, but the upside momentum is not picking up at the highs.
The formation of back to back lacklustre type candle pattern as per weekly timeframe is not suggesting healthy uptrend at the new highs. Though, there is no confirmation of any reversal pattern at the highs, but the danger of beginning of downward correction from the highs is not ruled out.
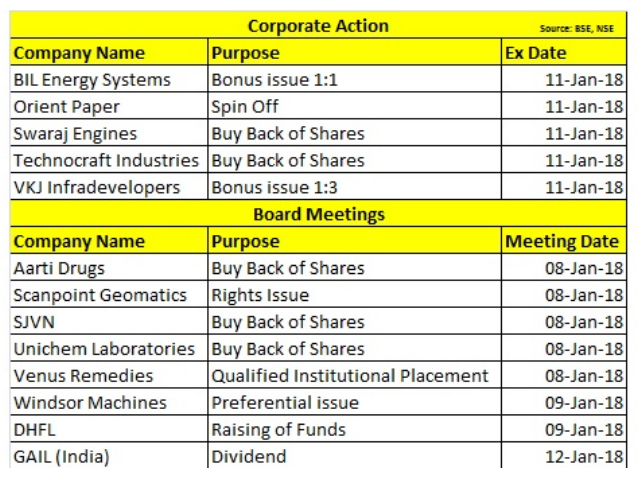
Corporate Action
Stocks in Focus
On Monday, Goa Carbon is expected to react positively to its Q3 earnings. It has posted net profit at Rs 22.50 crore against net loss of Rs 0.93 crore in year-ago and revenue more than doubled to Rs 186.6 crore from Rs 82 crore YoY.
Tata Steel's India production and sales in Q3FY18 were at 3.24 million tonnes and 3.30 million tonnes (provisional data), higher compared with 3.03 million tonnes and 3.08 million tonnes in Q2FY18, respectively. Europe steel production increased to 2.68 million tonnes (provisional) from 2.60 million tonnes but sales declined to 2.41 million tonnes from 2.60 million tonnes YoY.
Uttam Galva Steels reported loss at Rs 179.96 crore for October-December quarter 2017 against loss of Rs 257.28 crore in year-ago and revenue declined sharply to Rs 666.90 crore from Rs 1,035.61 crore YoY.
Sobha during December quarter achieved new sales volume of 9.33 lakh square feet (valued at Rs 750.9 crore) with an average realisation of Rs 8,045 per square feet, which is the highest every quarterly sales performance in terms of value and average realisation. Sales volume increased 8.4 percent and sales value 11.2 percent QoQ; and 52 percent & 92 percent YoY.
Lanco Infratech's shareholding in subsidiary Lanco Kondapalli Power reduced to 28.15 percent from 58.91 percent and hence, lenders' controlling stake stood at 52.21 percent after strategic debt restructuring.
NBCC shares may also react positively as the company has received contract from Ecotourism Development Corporation of Uttarakhand, Dehradun for construction of Kotdwar-Ramnagar Kandi Road amounting Rs 2,000 crore.
NACL Industries said the board of directors approved to raise funds to the tune of Rs 300 crore for meeting its growth plans.
Den Networks has entered into an agreement with cable TV distribution company VBS Digital Distribution Network (VBS) for acquiring 51 percent stake in VBS for Rs 2.64 crore.
Visa Steel is in discussion with SBI for settlement after the SBI filed an application with National Company Law Tribunal Kolkata to initiate corporate insolvency resolution process for the company under Insolvency & Bankruptcy Code.
Global Cues
Europe's industrial sentiment for December and retail sales for November will be announced on Monday, followed by unemployment rate for November on Tuesday.
China's December CPI and US' gasoline production will be released on Wednesday while Europe's industrial production for November and US' initial jobless claims will be announced on Thursday. European Central Bank will also publish account of monetary policy meeting on Thursday.
US' CPI and retail sales data for December will be declared on Friday.
MORE WILL UPDATE SOON!!