Monday, 29 July 2019

IndianMarketPulse Wins against Bear today in a Buy call........

IndianMarketPulse Wins against Bear today in a Buy call........

Still Confused to Join our Team .......

Don't Worry.....

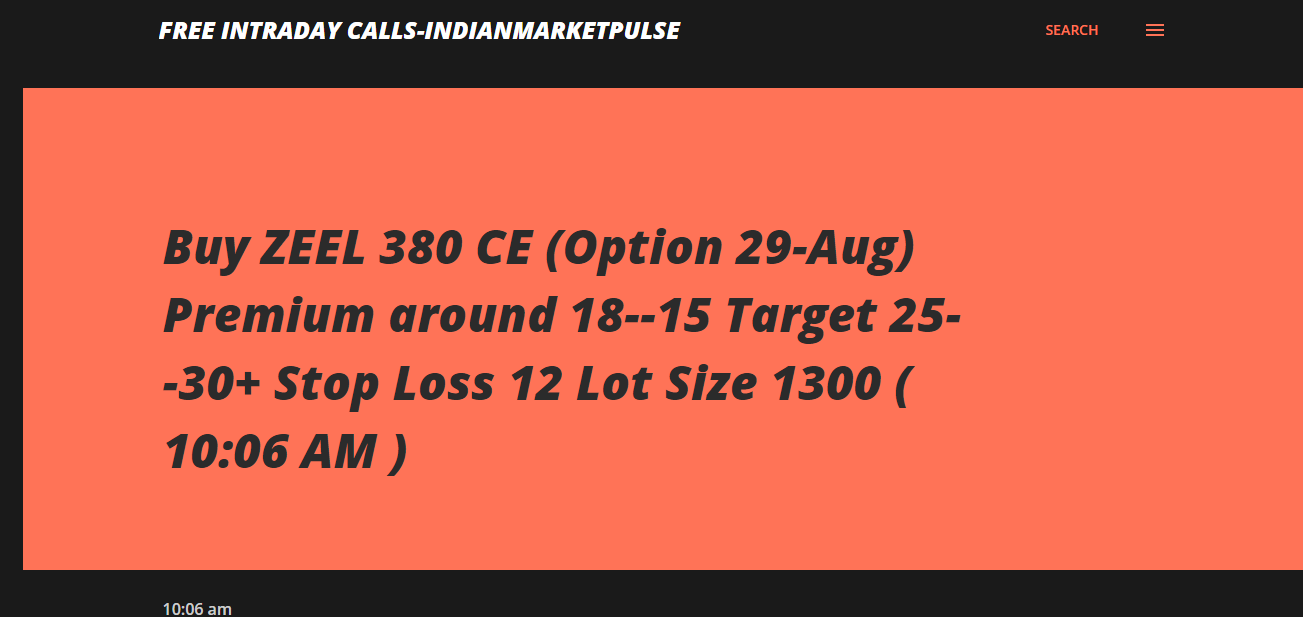
Look at the call we had given today.....

We had Given a call to Buy ZeeL 380 CE (Option 29-Aug) at a premium around 18--15 for the target of 25--30+  With a stop loss of 12.0....

Our called proved fruitful even in bear market and we minted profit......It Made a high of 36 AND NOW TRADING AT 33...... 

Profit of Rs 15600 in  Lot...............

We Believe in sound research and hope you minted profit in this call.....

This call was given free in our blog.......


MORE WILL UPDATE SOON!!


Technical View:29th July Strategy:

29th July Strategy:

Global: Neutral
FII: Negative
DII: Positive
F&O: Neutral
‪Sentiment: Cautious
Trend: Negative

Nifty 11225-11350 small day range,    Medium range 11200-11400

BankNifty 29200-29375 small day range,   Medium range 29075-29500,    Bigger range 28900-29650

For Existing Long Positions:
Nifty intraday SL 11200 n closing 11250
BankNifty intraday SL 29200 n closing 28950

For Existing Short Positions:
Nifty intraday n Closing SL 11375
BankNifty intraday n Closing SL 29500

For New Positions:
Sell Nifty near 11350:
SL 11400 Tgt 11300, 11275

Buy Nifty in 11225-11250 range:
SL 11200 Tgt 11300, 11325

Sell BankNifty in 29500-29600 range:
SL 29775 TGT 29375, 29200

Buy BankNifty in 28950-29075 range:
SL 28850 TGT 29200, 29325

PCR 1.37, VIX 12.13

MORE WILL UPDATE SOON!!

Today's Outlook

SGX Nifty is at 11,306, down by 23 points. For today, expect some more consolidation on the index, while broader markets could see another leg up as valuations become extremely attractive for the medium term.

Image result for BROKERAGE

Global markets: Asian indices opened weak even as the US indices closed at fresh new highs led by the S&P 500 & the Nasdaq. The Japanese Nikkei saw cuts of 100 points in early trade as strength in the yen hurt exporters. Markets will be keenly awaiting progress of trade talks between US/China and the Federal Reserve action on rates with a rate cut on the cards after 2008.

US markets close with gains as Nasdaq continues to hit fresh new all-time highs. Technology stocks see fresh highs as Amazon and Microsoft lead the gainers. Oil prices remain range-bound as supplies see upsurge while Iran tensions keep prices from falling. All eyes on Federal Reserve meet this week as 25 bps rate cut already discounted.

FII/DII Data: In yesterday’s trading session FIIs sold 1503 crores worth of stock in cash whereas DIIs bought 1918 crores worth of stock. In the derivative market, FIIs sold 1049 crores of Index futures and sold 1007 crores worth of Index options. In the Stock futures segment, FIIs sold 721 crores worth of stock futures and bought 126 crores stock options.

FII View: In Index future segment, FIIs index future long/short ratio stood at 0.6x vs 0.8x with addition of short positions to the tune of 9751 contracts. However, on the Index option’s front, they created net buying positions in both call and put options, indicating an expectation of volatility.

MORE WILL UPDATE SOON!!

Bank Nifty likely to see a bounce: Deploy ‘Long Call Butterfly Spread’ this week

Amid recent weakness, Bank Nifty has come down reasonably closer to the Put congestion.

The July expiry week kept traders on the edge. The market has been under pressure since Budget 2019 and benchmark indices closed the week with losses of over 1 percent each.
The rollovers to the August series, especially in the indices, remained low by around 3 percent and as a result, we did see a 7 percent drop expiry-over-expiry in the Nifty futures and an approximate 20 percent drop in the futures open interest of the Bank Nifty.
This open interest activity, alongside a reduction in price, can be reasonably termed as long unwinding.
The equation on the stock futures side was not a lot different, either with almost 36 percent of the participating stocks unwinding longs, while about 40 percent of the stocks added short or either carried forward short positions.
In the series which saw Nifty dropping by about 5 percent, sector-wise secularism on the long side was not visible.
If we were to slice the stock futures open interest data, Jindal Steel from metals, RBL Bank from private banks, Bajaj twins from the NBFC space were major drags on the short side, while PVR pushed the media sector into the long side.
One more notable observation is that the slow and steady fall did bring a lot of strong long heavy structured futures, especially on the banking side, closer to their respective heaviest Put OI base.
Amid recent weakness, the Bank Nifty has come down reasonably closer to the Put congestion. For the first time in recent weeks, the OIPCR for Bank Nifty is on the bullish side of neutrality, which indicates an expectation of longs to be reinstated, hence a Long Call Butterfly is advised.
Long Call Butterfly Spread is a moderately bullish strategy when executed with higher strikes than the current market price. It offers decent risk-to-reward ratio for investors with a low cost.
In this, we are selling two Calls close to the expected level on the higher side and Buying equidistant Calls, one of the higher, and one on the lower side of the strike sold.
As we are trading weekly options, faster time decay will be beneficial to the strategy. Maximum profit is made if the index closes at the strike of the option sold.
11
12
MORE WILL UPDATE SOON!!

Market Live: Nifty below 11,250, Sensex trades lower; auto, metal under pressure

Among sectors, except FMCG and IT all other indices are trading lower led by the auto, metal, pharma, energy and infra.

 Image result for BROKERAGE
Brokerages View:
Goldman Sachs on Maruti Suzuki

Maintain buy, target at Rs 7210 per share
Q1 results above estimates on cost control; buy on weakness
See EBITDA margin to have bottomed out as we expect better volume hereon

Citi on Maruti Suzuki

Buy call on the stock with target at Rs 7,400 per share
Q1 results a modest beat but near-term outlook gloomy
Co would likely outperform given sustained market share & balance sheet strength

IDFC Securities on Maruti Suzuki

Outperform rating with target at Rs 6,400 per share
Demand environment continues to remain weak with no overt signs of a recovery
Expect pressure on margin to continue in the near-term

CLSA on Maruti Suzuki

Maintain buy call with target at Rs 7,400 per share
Maruti reported weak q1 results as volume fell 18% YoY
Believe Maruti is a better way to play a potential demand recovery

UBS on Maruti Suzuki

Sell call with target at Rs 5800 per share
Q1 a consensus miss amid a tough environment
EBITDA below consensus, adjusting for estimated AS-116 impact

CIMB on Maruti Suzuki

Reiterate add rating with target at Rs 7,776 per share
Q1 EPS fell 20% QoQ In-line with consensus but 26% above estimate
Key risks are fuel price spike impacting car industry demand

Kotak Institutional Equities on Escorts

Maintain buy call; target cut to Rs 910 from Rs 1,000 per share
Co reported a 23% YoY decline in EBITDA mainly led by decline in tractor volume 
Believe the tractor segment has least headwinds related to cost increase

Credit Suisse on Escorts

Outperform rating with target at Rs 920 per share
Q1 headline numbers were broadly in-line with estimates

Nomura on Jubilant Life

Maintain buy call on the stock; raise target to Rs 661 from Rs 660 per share
Q1 EBITDA up 21% QoQ but 1% below our estimate

UBS on Bajaj Auto 

Maintain sell, target at Rs 2,400 
Q1FY20 in-line but market share plateauing despite aggressive pricing
High inventory adds to downside risk

IDFC Securities on Bajaj Auto 

Maintain underperform, target at Rs 2,400 per share 
Company’s strategy of cutting product prices to gain market share may benefit it over long term
Key upside would be a stronger-than-expected export market growth 

Kotak Institutional Equities on Bajaj Auto 

Maintain reduce, target cut to Rs 2,500 from Rs 2,700 per share
Slowdown led by a weak rural economy & sharp rise in regulatory costs

Nomura on Bajaj Auto 

Maintain neutral; target at Rs 2,836 per share
Q1 results in-line; growth slowing down 
Margin headwinds remain from adverse mix & regulatory cost pressures

Credit Suisse on Bajaj Auto 

Underperform, target at Rs 2,330 per share
Increasing competitive intensity in exports could jeopardise company’s profit
Cut FY20/FY21E EPS by 5%/8%, factoring in the further cautious outlook

Morgan Stanley on Bajaj Auto

Remain equal-weight with target at Rs 2,646 per share
Co Posted an in-line quarter 
EVs & emission regime change are key risks to the business

CLSA on Bajaj Auto

Fine tune our estimates & retain sell call with target at Rs 2,275 per share
Muted Q1 but better than estimates
See risk to 2-wheeler exports given the weakening global economic outlook

Jefferies on Bajaj Auto

Maintain underperform rating with target at Rs 2,430 per share
Management expects negative growth in domestic 2-wheeler industry for short-term
Adjusting for A/Cing changes, Q1 revenue was ahead, EBITDA in-line & margin below estimates

CLSA on ICICI Bank

Co is a high-conviction buy with target at Rs 530 per share
Q1 PAT tad below estimates due to higher provisions & higher tax
Trim earnings but see an earnings turnaround ahead & RoE rising to 15-16%

Jefferies on ICICI Bank

Retain buy call on the stock; raise target to Rs 480 from Rs 455 per share
Steady Q1 with core PPoP driven by better loan growth & steady margin
Fees were negatively impacted by lower mutual fund distribution fee
Expect improvement in core op profit; standalone RoE likely to be over 16% by FY21

Jefferies on JSW Steel

Retain underperform; cut target to Rs 216 from Rs 233 per share
Cut our FY20-21e EBITDA by 2-3%
Q1 EBITDA missed our estimate; margin was in-line, but volume disappointed

CLSA on JSW Steel

Cut our FY20-21 EPS by 4-5%
Retain sell rating; cut target to Rs 200 from Rs 225 per share

CLSA on autos

Believe govt’s proposal of higher registration fee is unlikely to boost auto demand
Believe regulatory costs are adding up for the Indian auto industry
Entered 2019 with a cautious view on autos & see few reasons to change it
Have sell ratings on 70% of our auto coverage; recommend underweight stance on sector.


MORE WILL UPDATE SOON!!

Rupee opens lower at 68.94 per dollar

On July 26 the rupee ended 15 paise higher at 68.89 against the US dollar, snapping its four days of losses following a recovery in the domestic equity market.Image result for usd inr


The Indian rupee opened marginally lower at 68.94 per dollar on Monday against Friday's close 68.90.
On July 26 the rupee ended 15 paise higher at 68.89 against the US dollar, snapping its four days of losses following a recovery in the domestic equity market.
MORE WILL UPDATE SOON!!

Stocks in the news: ICICI Bank, Cadila Health, Mahindra Life, Vedanta, Uflex, Granules, NHPC

Maruti Suzuki | Allahabad Bank | Future Lifestyle Fashions | ICICI Bank | Power Mech Projects | Manpasand Beverages and Usha Martin are stocks which are in news today.

 Image result for stock in news

Here are the stocks that are in news today:
Results Today: Dr Reddy’s Laboratories, DLF, IRB InvIT Fund, Supreme Industries, IFB Agro Industries, Bank of Maharashtra, General Insurance Corporation of India, Navin Fluorine International, Kingfa Science & Technology (India), Sanofi India, Bharat Electronics, Orient Cement, GHCL, Lloyds Steels Industries, India Grid Trust, Gokaldas Exports, Adroit Infotech, Sun Pharma Advanced Research Company, Century Enka, JMC Projects (India), Castrol India, Dalmia Bharat Sugar, Shriram City Union Finance, Chennai Petroleum Corporation, Kansai Nerolac Paints, Rane Engine Valve, Transport Corporation of India, Alembic Pharmaceuticals, Tata Sponge Iron, Cochin Shipyard, Shalby, AYM Syntex, Strides Pharma Science, V2 Retail, Valecha Engineering, Indian Card Clothing Company, EID Parry India, KPR Mill, Muthoot Capital Services
Unichem Labs Q1: Consolidated net loss at Rs 6.2 crore versus loss of Rs 20.4 crore, revenue up 23.4 percent at Rs 297.7 crore versus Rs 241.2 crore, YoY
Escorts Q1: Consolidated net profit down 27.6 percent at Rs 87.6 crore versus Rs 121 crore, revenue down 5.8 percent at Rs 1,440.5 crore versus Rs 1,529 crore, YoY
ICICI Bank Q1: Net profit at Rs 1,908 crore versus loss of Rs 119.5 crore, NII up 26.8 percent at Rs 7,737.4 crore versus Rs 6,102 crore, YoY
Eris Life Q1: Cons net profit up 17.4 percent at Rs 84 crore versus Rs 71.5 crore, revenue up 9.4 percent at Rs 274 crore versus Rs 250.7 crore, YoY
Havells India Q1: Consolidated net profit down 16percent at Rs 177.1 crore versus Rs 211.2 crore, revenue up 4.5 percent at Rs 2,717 crore versus Rs 2,600.7 crore, YoY
Vedanta Q1: Cons net profit falls 11.9% at Rs 1,351 crore versus Rs 1,533 crore, revenue falls 3.7% at Rs 21,374 crore versus Rs 22,206 crore, YoY
TeamLease Services Q1: Cons net profit down 13.8% at Rs 18.79 crore verus Rs 21.81 crore, revenue up 21.9% at Rs 1,251.23 crore versus Rs 1,026.57 crore, YoY
Mahindra Lifespace Q1: Cons net profit falls 51.3% at Rs 13.11 crore against Rs 26.90 crore, revenue falls 31% at Rs 106.22 crore versus Rs 153.95 crore, YoY
ABB Q2: Cons net profit at Rs 130.4 crore, revenue at Rs 1,725.8 crore, EBITDA at Rs 123.9 crore
Vodafone Idea Q1: Net loss at Rs 4,873.9 crore against loss of Rs 4,881.9 crore, revenue at Rs 11,270 crore versus Rs 11,775 crore, QoQ
India Ratings and Research assigned a long-term issuer rating of IND AA to the existing/proposed bank facilities of Tata Sponge Iron with Stable outlook is stable.
India Ratings upgraded Usha Martin's long term rating from existing IND BB+ to IND BBB+. Outlook stable.
CRISIL assigned CRISIL A1+ rating on Rs 300 crore commercial paper of Navneet Education
CRISIL upgraded the long-term rating of Aarti Drugs from CRISIL A/Positive to CRISIL 6+/Stable
ICRA re-affirmed the long term credit rating for Rs 344.87 crore line of credit of V-Guard Industries at ICRA AA
Manpasand Beverages: Arrested officials released on bail by Gujarat High Court
Cadila Healthcare: USFDA clears Ankleshwar unit with no observations
NHPC - Resolution Plan submitted by NHPC for Lanco Teesta Hydro Power has been approved by NCLT Bench, Hyderabad
Power Mech Projects: Andhra Pradesh State Project Director cancelled order worth Rs 512.78 crore
GTPL Hathway's chief financial officer Viren Thakkar resigned w.e.f. July 31, 2019
IDFC called off plan to sell entire equity stake held in IDFC Securities to The Chatterjee Group (TCG)
Oriental InfraTrust's chief executive officer Jitendra Kumar resigned w.e.f. August 31, 2019.
VST Industries elelcts Naresh Kumar Sethi as non-executive chairman
Remsons Industries approved resignation of Anil Kumar Agrawal as director finance and CFO and appointed Subhash Vishwakarma as chief financial officer of the company w.e.f. August 01, 2019.
Maruti Suzuki introduced CNG Variant in Ertiga and Tour M
Uflex has entered into an agreement to disinvest its 82% stake in Utech Developers, a wholly owned subsidiary
Future Lifestyle Fashions approved the issue of 64,79,481 equity shares at a issue price of Rs 463 per quity share on preferential basis to Apollo India Private Equity IV (Mauritius)
Granules India's Bonthapally facility at Hyderabad, Telangana completed the USFDA inspection with one 483 observation
Allahabad Bank to consider raising of equity capital of the bank through QIP /FPO /Rights Issue or in combination thereof, aggregating upto Rs 4000 crore on July 31, 2019
Sheela Foam approved to acquire Interplasp S.L., Spain.
Minda Industries redeemed commercial papers worth Rs 30 crore
MORE WILL UPDATE SOON!!

ICICI Bank gains 4% on robust Q1 nos; brokerages maintain buy

Research house Jefferies has retained buy call on the ICICI Bank and raised target price to Rs 480 from Rs 455 per share.


Share price of ICICI Bank gained 4.5 percent in the early trade after company posted better number in the quarter ended June 2019 (Q1FY20).
The bank posted a profit of Rs 1,908 crore in June quarter (Q1) over lower provisioning and healthy NII growth.
It was against a loss of Rs 119.55 crore reported in the year-ago period and a profit of Rs 969.06 crore in the previous quarter. The profit was partly impacted by lower other income.
Net interest income grew (NII) by 26.8 percent year-on-year to Rs 7,737.43 crore for quarter that ended on June 2019 with healthy loan growth of 15 percent YoY, which beat analyst expectations.
The year-on-year growth in domestic advances was 18 percent at June 2019.
Research house Jefferies has retained buy call on the ICICI Bank and raised target price to Rs 480 from Rs 455 per share.
According to Research house, the steady Q1 with core PPoP driven by better loan growth & steady margin, meanwhile the fees were negatively impacted by lower mutual fund distribution fee.
It expect improvement in core operating profit, while standalone RoE likely to be over 16% by FY21.
According to CLSA the company is a high-conviction buy with target at Rs 530 per share.
The company's Q1 PAT is tad below estimates due to higher provisions & higher tax, it said.
CLSA trims earnings but see an earnings turnaround ahead & RoE rising to 15-16 percent.
At 09:24 hrs ICICI Bank was quoting at Rs 427.10, up Rs 11.60, or 2.79 percent on the BSE.
MORE WILL UPDATE SOON!!

Friday, 26 July 2019

Our Yes Bank Call Hit Target again.....Patience wins Bears Loose against IndianMarketPulse


On 24th July 2019 we had given a call to Buy Yes Bank  Future call (29-Aug) around premium of 91--90 for the target of 96+ ........

Look at the call as Today it made a high of  97.20  and now trading at 96.30.

Patience wins the trade.......

We made profit of Rs  11000 on 1  Lot........

This call was also given in cash segment also..

Hope You Minted Profit.

This call was given free on our blog and also along with chart analysis and all technical levels.

WE ARE STILL HOLDING FOR TARGET OF 106....ARE YOU???

Still Looking for trade or confused!!..............Don't Worry Join Our Team......

KEEP TRADING FOR FREE>Just Click on  link below


or

 E-Mail Us at indianmarketpulse@gmail.com 

MORE WILL UPDATE SOON!! 

Important Levels:

  Image result for Marketoutlook

26th July Strategy:

Global: Neutral
FII: Neutral
DII: Neutral
F&O: Neutral
‪Sentiment: Negative
Trend: Negative

Nifty 11225-11275 small day range, Medium range 11200-11300. Bigger Range 11100-11350

BankNifty 28925-29125 small day range, Medium range 28850-29250, Bigger range 28500-29350

Fresh downside risk opens if Nifty trades below 11200 n BankNifty below 28800

For Existing Long Positions:

Nifty intraday n closing SL 11200
BankNifty intraday n closing SL 28800

For Existing Short Positions:

Nifty intraday n Closing SL 11375
BankNifty intraday n Closing SL 29300

For New Positions:

Sell Nifty in 11325-11350 range:
SL 11400 Tgt 11300, 11275, 11250

Buy Nifty near 11200:
SL 11175 Tgt 11250, 11275

Sell BankNifty in 29200-29250 range:
SL 29350 TGT 29125, 29075, 28950

Buy BankNifty in 28850-28900 range:
SL 28800 TGT 29050, 29200, 29250

PCR 1.37
 VIX 12.63

SGX Nifty is at 11,282, down 19 points. Expect pull back today as over sold conditions set up broader markets  for a rally.
Nifty saw another weak day after a solid start with short covering pulling the indices to almost 100 points higher in the morning. Expiry of derivative contracts took its toll as volatility and weak sentiment dragged the index lower for the 6th consecutive day to end down 20 points. The undertone seems weak as consumption stocks and blue chips NBFCs bear the brunt of heavy foreign selling. Autos, metals and PSU banks were the main losers while pharma and IT led the gainers.

US Market: US markets close with losses on the back of reaction to earnings with profit booking emerging after scaling fresh all time highs. US$ witnesses strength which sees bond yields rise to 2.10%. Oil prices continue to trade range bound closer to Brent at US$63. Federal Reserve rate cut will set the tone for markets globally with 25 basis points cut built in and guidance being the key.

Asian Market: Asian indices opened weak with the Japanese Nikkei trading lower by nearly 100 points.The Asian indices have been seeing very range bound trade with a negative bias as growth numbers are seeing visible threat of slowdown with consumption spending at the lowest in last 3 years. For today, expect weekend blues to see quiet trade as all attention shifts to US Central bank on rates.

Important results today: Maruti, Bajaj Auto, Punjab National Bank, Vedanta, JSW Steel

Jubilant Life Sciences, Mangalam Drugs, Music Broadcast, Teamlease Services, KPIT Technologies will be announcing its Q1 numbers.

Quarterly Results Quarterly results that are expected today include Maruti Suzuki India, Bajaj Auto, Punjab National Bank, Vedanta, JSW Steel, Tilaknagar Industries, Supreme Petrochem, Usha Martin, Polycab India, ABB India, Oriental Carbon, Elecon Engineering Company, Astec LifeSciences, Plastiblends India, Atul, Kalyani Forge, Balaji Amines, Confidence Petroleum India, VST Industries, Puravankara.

Jubilant Life Sciences, Mangalam Drugs, Music Broadcast, Teamlease Services, KPIT Technologies, Aarti Drugs, Vodafone Idea, DIC India, Indraprastha Medical Corporation, Bajaj Holdings, Alicon Castalloy, Mahindra Lifespace Developers will be announcing its Q1 numbers.

Here is the street expectation for the companies:

Maruti Suzuki Consensus estimates for Q1FY20E:
Revenue – Rs 19,373cr, down 14 yoy, 18% yoy volume decline due to weak demand, expect ASP to improve on qoq basis.
EBITDA – Rs 2,129cr, down by 36.5% yoy; due to negative operating leverage, higher discounts and weak INR.
EBITDA Margin – 11%, contraction of 390bps yoy.
Profit – Rs1,634cr, down 17% yoy; higher investment income to limit PAT decline, despite an estimated 36.5% yoy fall in EBITDA.
Bajaj Auto Consensus estimates for Q1FY20E:
Revenue – Rs7,460cr, flat yoy, mere 2% yoy volume growth amid weak demand environment, expect overall ASP to fall 3.5% qoq.
EBITDA – Rs1137cr, down by 11% yoy; due to aggressive pricing in 2Ws and weak mix.
EBITDA Margin – 15.2%, contraction of 202bps yoy.
Profit – Rs1,093cr, down 2% yoy; higher investment income to limit PAT decline to 2% yoy, despite estimated 11% yoy fall in EBITDA.
JSW Steel consensus estimates for Q1FY20E:
Consolidated Revenue – Rs21,053cr, flat on yoy basis owing to flattish volumes and slightly lower realisations.
EBITDA – Rs3,719cr, down 27.2% yoy, on lower realisations and higher ore prices.
EBITDA Margin – 18.1%, contraction of ~680bps yoy
PAT – Rs1,094cr, down 53.8% yoy

MORE WILL UPDATE SOON!!